
I have spent the week at Yale University where I was invited to take part in the summer crisis response workshop organized by Andrew Metrick of the Yale Programme on Financial Stability (YPFS). It was a fantastic and formative experience with great participants from the Federal Reserve System, the FDIC, the ECB and other central banks.
But this week, I will focus on
1. French politics after the comeback of Marine Le Pen
2. NATO’s summit and the fraying of the Franco-German defence-industrial core
3. Financial crisis preparedness and some transatlantic reflections
4. Spain/Cuerpo’s common borrowing non-paper and why it won’t fly
+++++++++
1. French politics and the comeback of Marine Le Pen
I had written last week that my central scenario had become a lighter sentence for Le Pen and her ability to run, so I was not surprised by the Court of Appeal’s decision. As I wrote then, I also think Marine Le Pen is a much stronger candidate than Jordan Bardella, and this is now reflected in the polls, where recent surveys suggest she is doing better than Bardella would have done.
What I find more interesting legally and politically is the fact that Marine Le Pen is also appealing the Court of Appeal’s decision, which I was not expecting at all. Indeed, in principle, taking the case to the Cassation Court (the supreme judicial court for such criminal cases) would upend the Court of Appeal’s decision and leave in place the first-instance ruling, with the five-year ineligibility sentence and immediate application.
What Le Pen’s legal team is attempting is a real coup de force on the judicial order, and it seems to be working. Not content with having secured a lighter sentence, her legal team is also appealing the decision and forcing the Court to rule on her candidacy while letting her run. Indeed, the highest French case law (1993 and 2014) has established several times that, in the case of an appeal, the first-instance sentence applies. But these cases did not concern ineligibility sentences, and Rémy Heitz, the Public Prosecutor at the Court of Cassation, declared publicly on 9 July that Marine Le Pen would be able to run — suggesting a very significant change in jurisprudence.
What is striking on the whole with this case is both the strategy of Marine Le Pen to confront the legal order head-on and the clear signs from the political system in France that it is prepared to accommodate her running. Indeed, it is worth noting that no political party has objected to the lighter sentence, and worth remembering that in France the public prosecution is not independent and answers directly to the Minister of Justice.
2. NATO’s Ankara summit and the fraying of the Franco-German defence-industrial core
NATO leaders met in Ankara on 7-8 July under the now-familiar formula of record spending pledges and Trump-adjacent stagecraft.
The bigger point underneath is that the Franco-German industrial core of European defence — the thing that was supposed to give strategic autonomy an actual production base — is breaking down. I had talked about the SCAF collapse for two years, but this could have been largely irrelevant if the rest of the industrial core was coming together — and it is not. I had mentioned after its collapse that Germany’s behaviour would be important to monitor, and we seem to be headed for the worse combination of more American procurement (F-35s/Tomahawks) and complete renationalisation of the industrial base.
Indeed, Germany’s most striking response to the death of the FCAS has been to launch a new German combat aircraft programme that includes Airbus as co-lead, alongside an eight-firm German consortium. The so-called Team Gen 6 will be centred around Airbus and awaits a formal decision by the autumn. This will potentially amount to the “rewriting of Airbus’s internal balance” by hijacking the civilian revenues of Airbus to develop a new military project to compete with Dassault. Having lost design authority on the one programme that mattered most, Germany is now working two levers simultaneously — pushing for a “fair share” in the Next-Generation Single-Aisle, the eventual A320 replacement that will define Airbus’s commercial-aircraft workshare for the next generation, and positioning Airbus’s German-anchored consortium as prime contractor on a national fighter track that would, for the first time, put German industry in the design-authority seat.
Neither is resolved, but the direction of travel is clear: Berlin is no longer content to be the paying co-owner while France holds the pen. Germany had long viewed Airbus as an unbalanced relationship, and it now seems intent on using its unlimited defence budget to rewrite the pre-nup.
The rewiring extends beyond the fighter jet programme. On 1 July, KNDS shelved its planned Paris-Frankfurt dual listing. The proximate cause was a valuation gap between institutional investors’ demand and the Wegmann family (KNDS’s German co-owner). In principle, the Franco-German tank project principally run by KNDS is unaffected by this. But the delay does undermine the governance rebalancing that was meant to formalise Franco-German parity: it leaves KNDS on its old 50/50 capital structure (French state via Giat Industries, Wegmann family privately) rather than the new 40/40/20 structure with both governments as equal, direct shareholders. The untold story is that Germany is growing uncomfortable with Franco-German co-ownership and joint defence projects. Berlin has launched its own parallel Leopard 3 track with Rheinmetall and a German-led twelve-country next-generation tank initiative that pointedly excludes France. As I have written before, my scenario is the slow death of the MGCS and the rise of Rheinmetall’s Leopard 3 as an alternative.
This logic extends to space and satellites. In March, it was announced that Airbus Defence and Space, OHB and Rheinmetall would seek to partner to develop an indigenous satellite constellation of up to 1,000 satellites for communication and reconnaissance. But in June, the company established to lead the project — OHB Rheinmetall Space Networks GmbH — excludes Airbus. It is no accident that, despite Germany’s intention to rewrite the internal balance inside Airbus, it ultimately did not include Airbus in this new project. With more than €30bn committed by 2030, this is the largest space/satellite project in Europe — almost an order of magnitude larger than the French-led Ariane 6 launcher platform.
This move towards space from Germany is not new and started in 2023, when Germany demanded to open the space market for small launchers. Berlin had reached a degree of frustration with ArianeGroup that could no longer be contained, in large part because the French leadership of Ariane entirely failed to see SpaceX and reusable launchers as a real alternative and real threat. Berlin will now seek to use the envelope of the European Space Agency to subsidise its own space start-ups (ISA, RFA), and with its new satellite launch programme, it will have a strong pipeline and enormous firepower.
Chart 1: France vs. German defense spending, Euros Billions
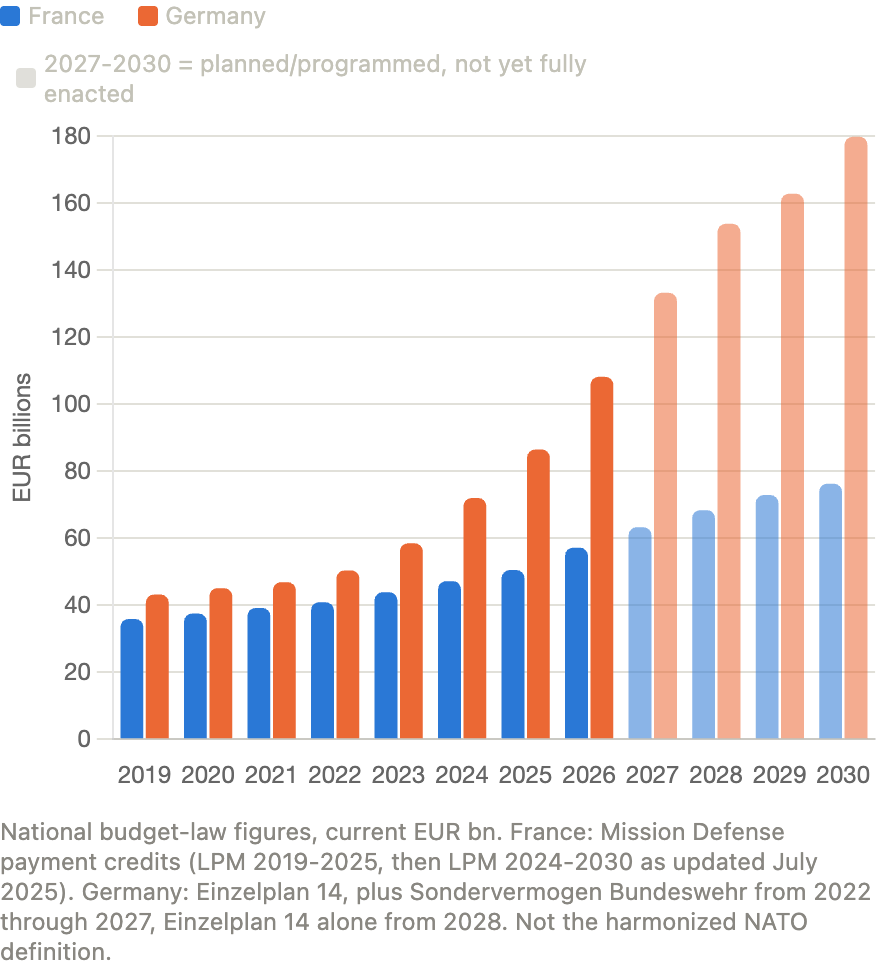
In this very tense Franco-German relationship, both countries are quietly seeking and competing for alternatives. France seems to have the upper hand for the time being, but it is unclear whether that will last given the extraordinary divergence in fiscal firepower over the coming years. I think it is very interesting to see how the Nordics, and in particular Sweden, may emerge as a European defence aggregator. They are both more closely connected to Ukraine than both France and Germany, and are increasingly at the heart of Nordic defence cooperation, which is probably at the forefront of European defence cooperation. If the Franco-German engine falters, the Nordic one might be able to take over.
Germany has signed a Letter of Intent with Sweden on 8 July, on the margins of the Ankara summit, covering air and missile defence, space, electronic warfare and AI — everything, notably, except a manned combat aircraft, though officials are not ruling out eventual work with Saab on that front either. Sweden’s rise as a leading European defence partner — rather than a well-armed neutral on the margins — is the other real story of the summer.
Stockholm finalised a $2.53bn sale of 16 new-build Gripen E fighters to Ukraine on 30 June, which will be partially built in Ukraine, on top of donating up to 16 Gripen from its own active fleet, cementing the Gripen as a genuine second European fighter option alongside the Eurofighter and Rafale at a moment when the sixth-generation programme meant to eventually replace both is lagging.
France is also moving fast with a deal for Naval Group frigates in May worth $4.2bn. The two countries also signed a Joint Declaration of Intent on Total Defence and Resilience in June, covering Arctic operations and space alongside the naval relationship. Ireland is the other beneficiary of the same French push: the 2026-2030 Joint Strategic Framework signed in February commits Dublin to roughly €2bn of French equipment — armoured vehicles, Naval Group maritime patrol cooperation — and, more unusually for a state with no real defence-industrial base of its own, to joint procurement with France.
Put together, this is not the picture of “Europe stepping up” that Macron and Merz both want to project, but it still leaves some hope for European integration, although not primarily through Franco-German defence leadership. Germany is rebalancing its defence-industrial dependence away from France. France is diversifying its own client base towards northern Europe. Overall, the assumption that European strategic autonomy would be built around a Franco-German industrial duopoly no longer holds, and the SAFE-regulation joint-procurement instrument is, if anything, accelerating a shift towards more numerous, more plurilateral, more transactional defence-industrial pairings, rather than consolidating around the old core and via EU institutions.
3. Some thoughts on financial crisis preparedness
The Yale workshop I attended was illuminating and largely based on the YPFS database cases and framework, and a tabletop exercise simulating an AI-bubble-implosion-led credit/banking crisis, forcing the type of crisis response developed during the Global Financial Crisis. On the whole, policymakers reacted well, but stabilising the US Treasury market was a much bigger challenge this time around.
What emerges from this weeklong workshop for me is an interesting schism between Europe and the US, with the Federal Reserve System still very focused on building/upgrading instruments to deliver liquidity in crisis times while the ECB has moved almost entirely to asset purchase programmes to tame market stress. There is in the US a broad feeling that the SVB and Signature Bank crises exposed some gaps in the Federal Reserve’s liquidity provision framework that need to be repaired. It is also striking to note that Europe has entirely moved to fixed-rate, full-allotment operations, while auctions are still a central feature of the US toolbox.
Finally, I had not paid enough attention to the rescue of Credit Suisse by the SNB, and how much of a missed opportunity it was for testing resolution plans and frameworks for GSIBs. With the benefit of hindsight, what emerges from this exercise, however, is the interesting way in which the Swiss National Bank decided to secure dollar liquidity at the height of the crisis. It did not use its standing USD swap line but rather its FIMA repos, to turn its Treasury holdings into cash. It is an odd choice of instrument given the known stabilising power of swap lines, and may suggest a slightly more conservative US approach towards swap lines. It is very much in keeping with the ECB’s attitude, which has been very conservative on the expansion of its swap line network and has chosen instead to expand the EUREP framework (equivalent to the Fed’s FIMA).
Finally, perhaps the most interesting short-term data point for me was seeing most of the Fed staff at the workshop somewhat relieved about institutional integrity after the first announcements and appointments by Chair Warsh.
4. Spain’s €850bn common borrowing pitch, and why European public goods remain the more promising route
Spain used Tuesday’s Eurogroup meeting to relaunch the common-debt debate, with economy minister Carlos Cuerpo presenting a non-paper advocating for the Commission to centralise part of member states’ national funding programmes, issuing bonds against its AAA rating and passing the proceeds back as loans. On paper the numbers are large — up to €850bn a year if all 27 states plus the ESM and EFSF participated, building towards a €5trn stock within five years. This pooled issuance would save around €25bn a year in borrowing costs. He was careful to frame this as a technical instrument to seek efficiency, and not as a mechanism for debt mutualisation.
Unsurprisingly, the reception in the room was cold. The Netherlands’ Eelco Heinen dismissed it outright — “there’s a debate about Eurobonds every day... the answer is always the same: no” — Finland’s Riikka Purra called shared debt “not the solution, and not an option,” and Germany has opposed eurobonds consistently under Merz, who has cited Constitutional Court constraints directly. Even Ireland, holding the rotating Council presidency and nominally sympathetic, deflected towards the MFF negotiation rather than endorse the idea. Eurogroup president Pierrakakis’s own verdict — “there is currently no consensus” — is as close to a formal burial as Brussels diplomatic language gets.
I have written about this extensively in the past, in response to the Blanchard/Ubide proposal, and I continue to consider that the more promising route is to stop asking for common debt in the abstract and start financing specific European public goods — integrated air and missile defence, satellites, secure cloud, cross-border energy grids.
This is precisely the logic behind the Finland-Netherlands-UK joint defence-financing initiative launched earlier this year, and it is no accident that the same governments most resistant to a general Spanish-style facility are the ones willing to capitalise a narrower defence-specific vehicle: the rationale shifts from solidarity, which triggers every distributional anxiety Berlin, The Hague and Helsinki have, to mutual self-interest and fiscal efficiency, which does not.
Happy to discuss,
The Russia LNG paragraph is the most structurally devastating section. The EU has spent more on Russian fossil fuels since February 2022 than it has given Ukraine in aid. That sentence should end every conversation about European strategic credibility until the numbers change. A continent positioning itself as the architect of Ukraine's post-war settlement while simultaneously being its adversary's largest energy customer faces a contradiction that no amount of summit communiqués can resolve.
The legal window closing in 2026-2027 doesn't soften this. European buyers sprinted to lock in Russian volumes before the ban, which tells you the actual priority. The ban doesn't demonstrate commitment. It demonstrates that commitment required a legal deadline to enforce what political will couldn't deliver voluntarily.
The RN risk deserves a louder alarm than it's getting. If Le Pen's party wins and creates an early France-EU confrontation, the entire European defence architecture that NATO just endorsed in Ankara sits on a fault line. France is Europe's only nuclear-armed EU member and its largest military. A France-EU showdown doesn't just slow the defence build. It structurally fragments the one capability Europe cannot replicate without Paris.
We mapped the European defence order book and procurement pipeline that this risk threatens directly: https://scenarica.substack.com/p/the-last-order-book